Maldives’ 40% Dollar Conversion Rule is a gift for Sri Lanka’s Tourism Sector
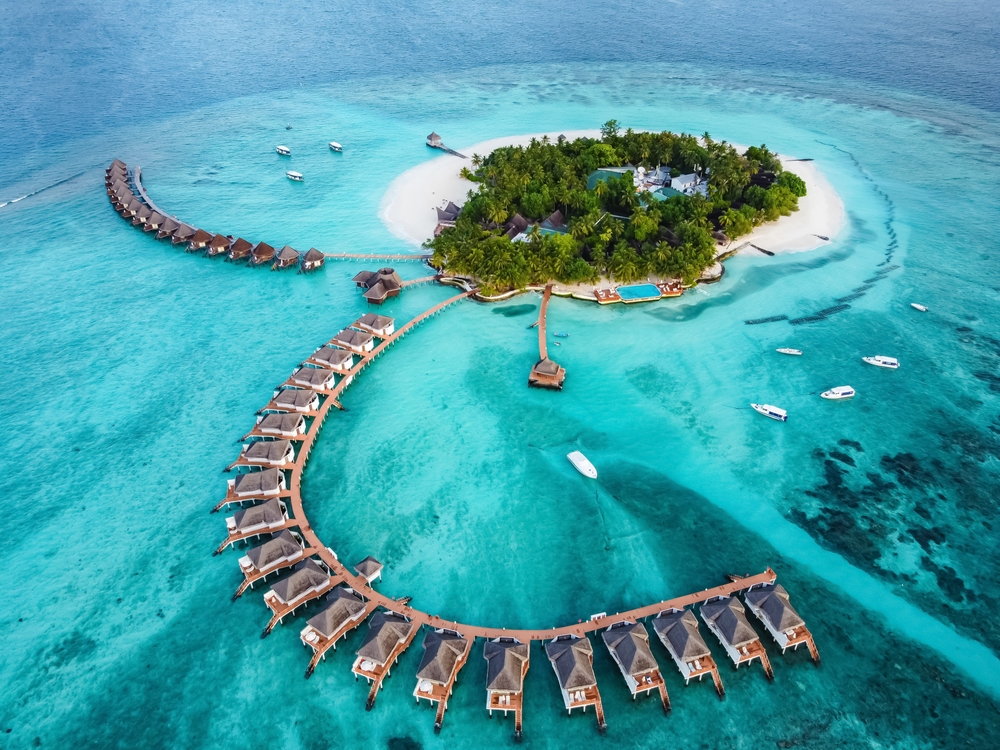
Sri Lanka and other regional players to benefit
By Jithendra Antonio
On 31 August 2026, President Mohamed Muizzu signed the First Amendment to the Foreign Currency Act into law, alongside six other pieces of legislation. The amendment came into force the very next day, on 1 September 2026. Buried in the fine print of a busy legislative week is a change that could reshape the competitive map of Indian Ocean tourism.
The headline number is stark, the mandatory foreign-currency conversion obligation for Category A Tourism Establishments, resorts, hotels and tourist vessels has doubled, from 20% to 40% of monthly gross sales. The amendment also scraps the old per-arrival option (USD 500 per tourist), raises the revenue threshold for “high-income entity” status from USD 15 million to USD 25 million, and introduces a new requirement that businesses obtain the Maldives Monetary Authority’s (MMA) prior approval before making or receiving foreign-currency payments for goods and services, outside a narrow set of exemptions such as salaries, dividends and related-party payments.
Taken individually, each of these is a technical tweak to monetary policy. Taken together, they amount to one of the most consequential regulatory interventions in Maldivian tourism in a generation — and one that the country’s competitors would be foolish to ignore.
Why 40% Is Not Like Any Other 40%
To understand why this figure matters so much, you have to understand the peculiar economics of a Maldivian resort. Unlike a hotel in Colombo, Phuket or Victoria, a Maldivian resort is not simply a business operating within a domestic supply chain that happens to also serve foreign guests. It is closer to an offshore platform that imports almost everything it needs to function.
By most industry estimates, upwards of 90% of a resort’s operating costs are denominated in US dollars. Imported food and beverage, spare parts, fuel, insurance, reinsurance, loan servicing on foreign-currency-denominated resort development debt, and, critically, the salaries of both expatriate and, increasingly, local staff, many of whom are paid partly or wholly in dollars. Resorts do not run on Rufiyaa. They run on dollars converted into Rufiyaa only for the narrow slice of domestic obligations- government fees, local taxes, a portion of local payroll that must be settled in the national currency.
This is the crux of the problem with the new rule. In most emerging markets, a forced conversion requirement is a nuisance. Exporters grumble, but the local banking system can usually recycle the converted currency back into the economy, including back to the exporter, in a reasonably liquid market for trade finance. Maldives does not have that recycling mechanism. Commercial banks in the Maldives do not open Letters of Credit or otherwise reliably sell dollars back to resorts to fund imports, the way banks in Sri Lanka or India routinely do for their exporters. Once a resort’s dollars are converted to Rufiyaa under this rule, that money is, for most practical operating purposes, gone. It cannot easily be turned back into the dollars the resort needs to pay its next shipment of Italian olive oil, its Singaporean spare-parts supplier, or the coupon on its offshore construction loan.
At a 20% conversion rate, this was already a drag. At 40%, it moves from “drag” to “structural threat.” A resort converting 40% of gross sales into a currency it functionally cannot use for the majority of its cost base is not paying a tax — it is absorbing a near-total loss on that portion of revenue. For a mid-market resort operating on already-thin margins after years of rising TGST, Green Tax, airport fees and land rent, that is not a rounding error. It is the difference between viability and closure.
A Policy With No Recycling Loop
The new prior-approval requirement compounds this. Before an amendment, a resort earning and needing dollars for imports could at least transact relatively freely with its suppliers. Now, every foreign-currency payment for goods and services — on both the paying and receiving side — requires MMA sign-off, unless it falls under the narrow carve-outs for salaries, dividends and related-party flows. This is a liquidity chokepoint layered on top of a conversion mandate, at precisely the moment resorts most need flexibility to manage dollar scarcity.
It is worth noting that this is not the first time the industry has raised the alarm. When the original Foreign Currency Act was introduced in 2024–25 with its 20% (or USD 500-per-tourist) requirement, more than 50 resort operators wrote directly to the MMA and the President’s Office warning of exactly this dynamic — uniform dollar quotas that ignored differences in average daily rates, complimentary stays and loan obligations. The Maldives Association of Tourism Industry (MATI) called the original rules “unacceptable.” The government pressed ahead regardless, and by early 2026 the MMA Governor was even publicly hinting that the conversion rate might eventually be reduced. Eighteen months later, it has instead been doubled.
The Region Is Watching — And So Are the Alternatives
This is where the story stops being a purely domestic Maldivian matter and becomes a regional competitiveness question.
Sri Lanka offers a useful contrast. Colombo has, since 2022, required hotels to accept payment from foreign guests only in foreign currency, but critically, that foreign currency goes into the hotel’s own Business Foreign Currency Account, from which the operator can pay international suppliers, service dollar-denominated debt and manage its own liquidity, subject only to a requirement to sell or bank it within a short window. The dollars stay usable. Sri Lankan tourism earnings, in the meantime, have kept climbing, touching roughly USD 2.66 billion in the first ten months of 2025 alone, while the destination has actively repositioned itself upmarket.
Seychelles and Thailand, though their regulatory regimes differ in detail, share the same basic feature that Maldives now lacks, hard-currency revenue earned by the tourism sector remains substantially available to the sector to fund its own hard-currency cost base. Neither imposes anything resembling a blanket 40%-of-gross-sales conversion mandate with no functioning repatriation channel.
For a certain segment of the market, international resort operators and management groups with the flexibility to allocate new development capital across the Indian Ocean and Southeast Asia, the calculation is not sentimental. If Maldives makes it structurally harder to fund operations in the currency those operations actually require, while comparable destinations do not, capital and new openings will tilt accordingly. The same logic applies to existing resort groups deciding where to commit expansion capex, and to high-end tour operators quietly steering allocation toward destinations where their partner properties are not fighting a currency mismatch. None of this happens overnight, and none of it will be announced as a policy response. It shows up two or three years later, in occupancy figures, in ADR growth rates, and in where the next wave of five-star openings actually breaks ground.
What This Means, Practically, for Regional Players
For destination marketing organisations and private-sector operators in Sri Lanka, Seychelles and Thailand, there is a genuine, opening here,
The pitch is currency stability, not just price. Resort investors and management companies increasingly care about the ability to operate in the currency they earn in. A destination that can credibly say “your dollar revenue stays usable as dollar revenue” has a structural argument that no amount of marketing spend in Malé can currently counter.
The competitive response should target capital allocation, not just tourist footfall. The immediate opportunity is less about poaching Maldives’ existing guest base — the products are not perfect substitutes — and more about capturing the next cycle of resort development and brand expansion decisions being made right now by groups weighing where to build.
Timing matters. The MMA Governor’s own comments in early 2026 suggest even the Maldivian authorities are aware this rate may prove unsustainable and could eventually be walked back. Any competitive positioning built on this differential has a shelf life; it should be pursued with urgency rather than treated as a permanent advantage.
Policy stability is now, itself, a selling point. A regulatory environment that has doubled a conversion mandate within roughly eighteen months of its original introduction, against explicit, documented industry objection — sends a signal about predictability that rival jurisdictions can credibly contrast themselves against, provided they can point to their own track record of consultation and stability.
A Policy Problem Dressed as a Monetary One
The Maldivian government’s underlying objective — building a resilient pool of foreign currency reserves and reducing dependence on informal exchange channels — is a legitimate one, and MMA has framed the amendment in exactly those terms. But policy tools have to fit the economy they are regulating. A conversion mandate that assumes resorts can function on Rufiyaa, in an economy that imports nearly everything a resort needs and offers no functioning dollar-recycling mechanism through the banking system, is not solving the reserves problem so much as exporting it — onto the balance sheets of the operators who generate those reserves in the first place.
Until Maldives builds the missing piece, a genuine mechanism for resorts to access foreign currency for legitimate operating needs, whether through LCs, a functioning interbank forex market, or negotiated exemptions calibrated to actual dollar cost structures — the gap between the 40% conversion requirement and the 90%-dollar-cost reality of running a resort will keep widening. And every month that gap persists is a month in which Colombo, Victoria and Phuket have a stronger story to tell the next investor deciding where the next five-star island resort gets built.
(The writer is a Consultant specialised in Data Analytics with a Special Focus on Sri Lanka’s Future Direction, and in the fields of Sustainable Energy, ESG, Investments and telecommunications. He can be reached at jithendra.antonio@gmail.com.)